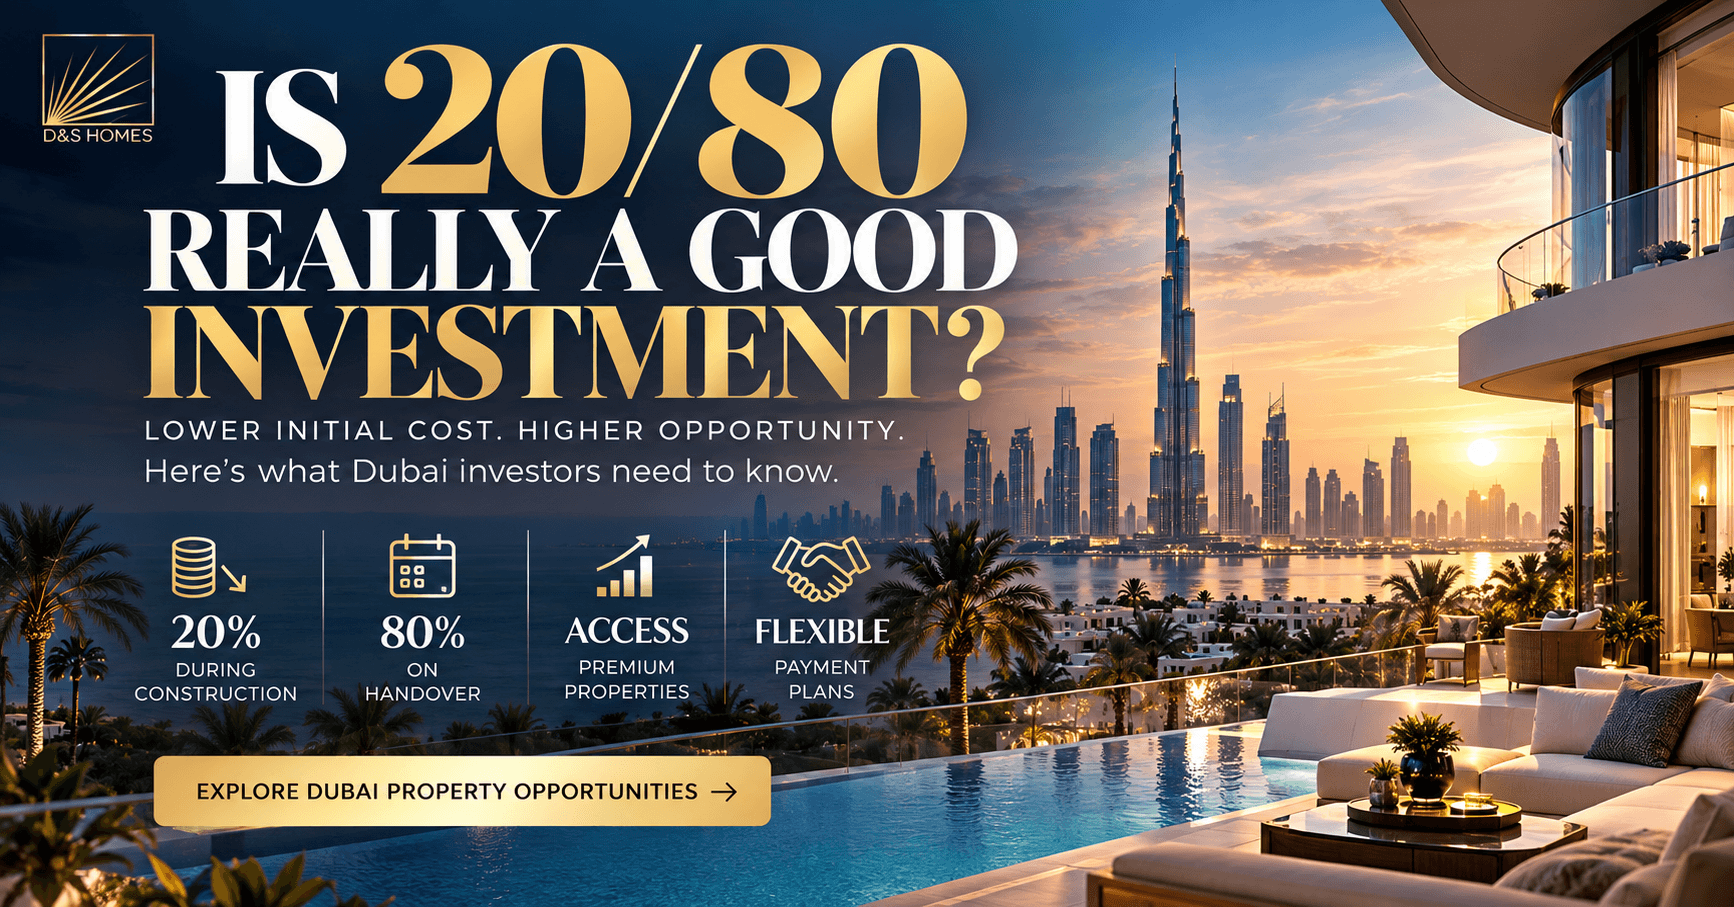
Pay 20% during construction and the remaining 80% at handover. On paper, it sounds like an easy way to buy a Dubai property without committing most of your capital upfront. But there is an important question every investor should ask before signing: does a flexible payment plan make the property itself a good investment?
The answer is not automatically yes. A Dubai 20/80 payment plan can improve liquidity and give buyers more time to prepare their capital. However, the payment structure is only one part of the investment equation. The developer, location, purchase price, rental potential, resale demand, completion timeline and your ability to fund the final payment can matter just as much.
For investors considering Dubai property, understanding the numbers behind the payment plan is therefore essential.
What Is a Dubai 20/80 Payment Plan?
A Dubai 20/80 payment plan generally means that the buyer pays approximately 20% of the purchase price during the construction period, while the remaining 80% becomes payable at handover or according to the developer’s agreed schedule.
The exact structure varies between developers and projects. Some plans may require a booking amount followed by instalments during construction. Others may include additional registration fees, service charges, or different percentages at specific construction milestones.
For example, consider a property priced at AED 2 million:
- 20% during construction = AED 400,000
- 80% remaining = AED 1.6 million
- Total purchase price = AED 2 million
The important point is simple: the 80% has not disappeared. It has merely been deferred.
Why Investors Like 20/80 Payment Plans
The biggest attraction of a Dubai 20/80 payment plan is capital efficiency. Instead of committing a large amount of cash immediately, an investor may retain more liquidity during the construction period.
1. More capital remains available
With only part of the purchase price required during construction, investors may have more cash available for other investments, business activities, emergency reserves or diversified assets.
That flexibility can be particularly useful for experienced investors who have a clear strategy for deploying their remaining capital.
2. More time to prepare for handover
A structured payment schedule can provide additional time to build savings, arrange financing or plan an exit strategy. Consequently, the investor may have several possible ways to prepare for the final payment.
3. Potential leverage without immediate full funding
Depending on eligibility, financing conditions and the specific project, a buyer may explore mortgage financing or other funding options closer to completion.
Nevertheless, financing should never be assumed. Approval depends on the buyer’s financial position, lender criteria, property characteristics and prevailing regulations.
What About the 80% at Handover?
This is where investors need to look beyond the headline.
A Dubai 20/80 payment plan can appear attractive because the initial commitment is relatively low compared with the eventual purchase price. However, the final 80% creates a substantial future obligation.
For a AED 2 million property, AED 1.6 million still needs to be funded.
Before committing, ask yourself four questions:
- Will I have enough cash available at handover?
- Would I qualify for financing if I need it?
- Could I sell or assign the property if my circumstances change?
- What happens if the property takes longer to sell or rent than expected?
These questions are often more important than the initial 20% payment.
Is a 20/80 Plan Better for Investors or End Users?
The answer depends on the buyer’s objective.
For an investor, a Dubai 20/80 payment plan may provide greater flexibility because capital remains available during construction. The investor can potentially use that period to build reserves, evaluate market conditions or prepare an exit strategy.
For an end user, the benefit may be different. A buyer purchasing a future home could use the construction period to arrange financing, sell an existing property or prepare for the eventual move.
However, neither buyer should confuse payment flexibility with investment quality.
Calculate the Investment, Not Just the Payment Plan
A property should be evaluated using its complete financial picture.
For a Dubai 20/80 payment plan, consider at least these factors:
- Purchase price: Is the property priced competitively against comparable properties?
- Location: Is there sustained demand from tenants and buyers?
- Rental potential: What realistic rent could the completed property achieve?
- Service charges: How could annual building or community costs affect net returns?
- Resale demand: Who is likely to buy the property from you later?
- Developer track record: Examine delivery history and project execution.
- Exit strategy: Know how you would sell, refinance or retain the property.
Most importantly, calculate returns using realistic assumptions rather than the developer’s headline projections alone.
Dubai Property Trends Investors Should Watch
Dubai’s real estate market continues to attract international investors because of its global connectivity, population growth, infrastructure investment and position as an international business and lifestyle destination.
At the same time, increased development activity means investors have more projects and payment structures to compare.
That creates an important shift in strategy: buyers have to compare the underlying asset, not simply the payment plan.
In other words, two properties can both advertise a 20/80 structure while having completely different investment characteristics.
Location and supply matter
Future supply can influence rental competition and resale values. Therefore, investors should examine the surrounding development pipeline, infrastructure, community amenities and expected tenant demand.
Rental demand matters after handover
The property eventually needs to perform in the real market. A beautiful off-plan development with an attractive payment structure still needs tenants or buyers when it is completed.
That is why location-level rental evidence and comparable transactions should form part of the due-diligence process.
When Can a Dubai 20/80 Payment Plan Make Sense?
A Dubai 20/80 payment plan can make sense when the buyer has a clear funding strategy and the underlying property satisfies their investment criteria.
For example, an investor may have sufficient liquidity to cover the initial instalments while simultaneously building capital for handover. Another investor may intend to use mortgage financing, subject to eligibility and future lending conditions.
A third investor may have an exit strategy that involves selling the property before completion, where the contractual terms and applicable regulations permit it.
In each case, the payment structure supports the strategy. It should not be the strategy itself.
The Biggest Mistake Investors Make
The biggest mistake is focusing on the percentage rather than the total financial commitment.
Seeing “20% down” can make a AED 2 million property feel like a AED 400,000 investment. It is not. The contractual purchase price remains AED 2 million, before applicable transaction and ownership costs.
Likewise, an attractive payment schedule cannot compensate for an overpriced property, weak rental demand, poor location or an unsuitable developer.
Before choosing a Dubai 20/80 payment plan, investors should therefore stress-test the entire investment.
What happens if handover is delayed? What happens if rental income is lower than expected? What happens if financing conditions change? What happens if you need to exit earlier than planned?
A strong investment plan should have answers to these questions before the purchase agreement is signed.
20/80 Is a Payment Structure, Not a Guarantee
The central lesson is straightforward: a Dubai 20/80 payment plan can be a useful financial structure, but it does not automatically make a property a good investment.
Its value comes from what the buyer does with the additional time and liquidity.
Used carefully, the structure can help investors manage capital, prepare for handover and potentially create a more flexible investment strategy. Used without proper planning, however, the deferred 80% can become a significant financial pressure.
Before investing, compare the complete numbers, understand the contractual obligations and assess the property independently of the payment plan.
Planning to Invest in Dubai Property?
If you are considering a Dubai 20/80 payment plan, don’t make your decision based on the payment schedule alone.
At Jarsmak Dubai Property Management, we help property investors look beyond the sales pitch and understand the practical side of owning property in Dubai. From evaluating investment opportunities and rental potential to ongoing property management, tenant support and reporting, our focus is helping overseas owners manage their Dubai property with greater clarity.
Looking at a 20/80 property in Dubai? Contact Jarsmak to discuss the property, payment structure, rental potential and long-term management considerations before you commit.
Speak With Jarsmak About Dubai Property
Investment decisions should be based on your individual financial circumstances, objectives and independent due diligence. Payment plans, financing availability, fees and contractual terms vary by project and developer and should be verified before purchase.